*Disclosure: This article is general education, not legal or financial advice. Credit repair can't remove accurate, timely information, results vary by file, and you can dispute errors with the credit bureaus yourself at no cost.*
Having a strong credit profile is an essential part of life in our society. Credit scores are extremely commonplace in all lending institutions and are vital in judging creditworthiness. These scores can be used for things such as employment and rental approvals. With that said, the following article helps readers understand how paying off their credit cards responsibly will help them with their overall credit file.
What's the deal with credit cards?
Simply put, paying off at least the minimum amount on your credit cards each month goes a long way in helping your credit. Not only does it help your credit but it also helps you avoid those pesky late fees. With all financial tips, there are a few things you have to watch out for.
While this may seem very straightforward, credit card companies use a lot of technical terminologies to confuse consumers. In this blog, we will try and help you understand the main definitions used in the credit card industry, and how you can make sure you are paying your bills by the correct date.
Each month you receive a credit card statement. Here are 5 main terminologies to watch out for in your next statement:
- Statement Balance: This refers to the amount due during this statement period. It may also be referred to as the new balance or outstanding balance.
- Minimum Payment Due: This refers to the lowest amount you can pay before the credit card due date. Depending on the card issuer, it may be a fixed amount or a percentage of your overall balance.
- Payment Due Date: This is the date that the payment is due. If the minimum payment is not made by this date, a late fee will be charged.
- Minimum Payment Warning: This will show you the time frame to pay off your balance by only paying the minimum amount each month. This will calculate the potential interest owed.
- Account Summary: This is a quick snapshot of your overall account. It will show how the current balance was calculated, starting with the previous month's balance, and subtracting recent payments and credits while adding purchases, fees, and any interest charges.
Additionally, there will be other details available on your credit card statement including your current balance, new purchases made during that billing cycle, fees, interest charges, and the rewards/perks available with the card if it is a cashback or rewards card. Knowing this information, there are a few different ways to pay off your credit card. Some of them include:
- Online Payment Via Bill Pay: Most credit card issuers will allow you to link your bank account (checking or savings) with your credit card account to make payments.
- Money Transfer: Some credit card issuers offer you the ability to wire transfer funds to pay off your card balance.
- Cash or Check: Depending on the issuer, you may be able to pay with cash at a physical teller or at an ATM. As well, you may be able to pay with a check either at a physical teller, an ATM, or on the lender's mobile app.
- ACH Check: If you are trying to pay your card off with ACH checks, you will need to first provide your card issuer with your banking and routing number. This can often be done online, over the phone, or at a local branch.
Each of these payment methods is a completely acceptable option, it is all a personal preference for how you choose to pay your credit cards. Once you find a method that works best for you, it is advised that you continue payment in this fashion to keep a streak of solid payment history. If you are utilizing online payments, it is advised to schedule recurring payment reminders in your calendar or enable autopayment on your mobile banking app.
Best time to pay your credit card bill?
This should be simple, right? Before the due date! Aside from the obvious response, you do have some flexibility over the timing of your credit card payment.
First and foremost, we strongly advise you to pay the entire statement by the due date. This is beneficial for a number of reasons, including the fact that it improves your credit and shows lenders that you are a responsible borrower. It's crucial to give yourself enough time for your payment to be processed, therefore it may be advantageous to make your payment a few days before the statement closure date (more on paying early later).
The period of time between you making a payment and the account displaying "paid" can vary since credit card issuers have different policies for how long they should wait before posting a payment to your account. It is important to confirm what constitutes an on-time payment and how long it takes for payments to deposit into your account with your specific bank.
For instance, if you choose to mail a check, would the provider consider your payment to be received on time if the letter is postmarked by the deadline, or does the provider need to have the check in hand by the specified cutoff date? These are the inquiries to make before applying for a certain card.
It's not necessary for you to pay the entire due debt straight away. Credit cards frequently—but not always—have a grace period, which is the interval between the end of your billing cycle and the deadline for paying your statement. You won't earn interest on purchases made during the previous payment cycle during this time. As we will cover below, the use of numerous payments is quite ideal in this situation.
We advise making at least the minimum payment by the same due date if you are unable to pay the entire statement balance. This might assist you in managing your credit card debt and preventing any costly late fees. If you utilize a card with a zero percent initial APR (annual percentage rate) offer and benefit from the zero percent interest and balance transfers, making minimum payments is a smart move. You'll have extra time before the bank assesses interest even though you'll still need to make the minimum payments each month to avoid late fees.
Paying your credit card bill off early
Some prefer to pay off their accounts ahead of time so that when the bank generates the statement, it will show a $0 balance. This is not necessary as long as you have a grace period because you won't save any money on interest. Paying early, nevertheless, can assist in lowering your overall credit usage, which is the proportion between your entire credit card debt and total credit limit, if you're looking to raise your credit score.
Carrying balances on your credit cards
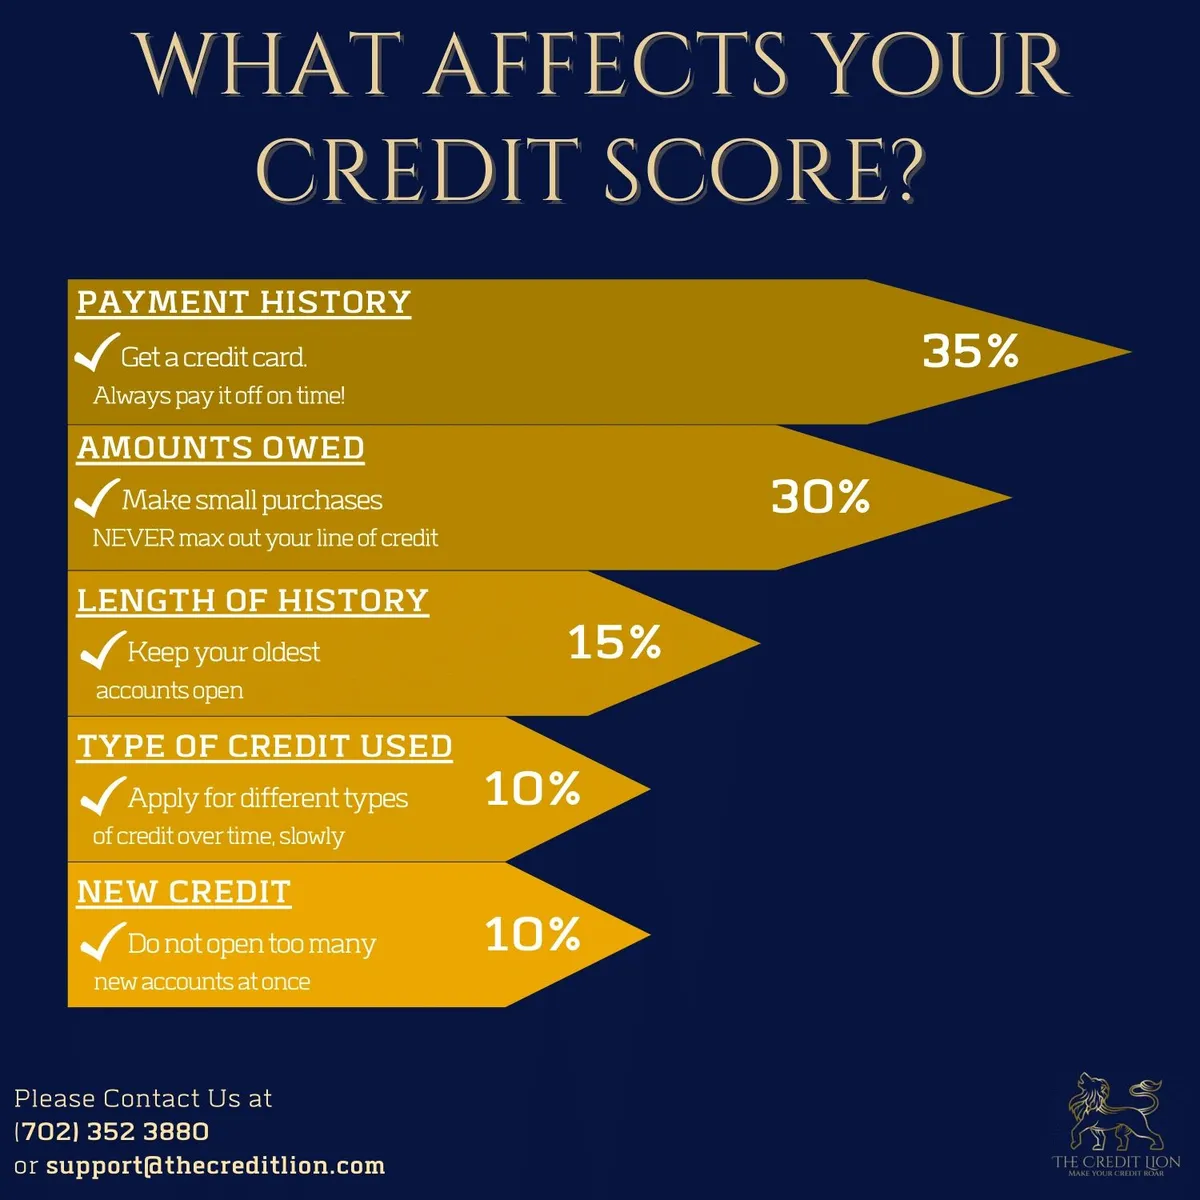
A misconception of many is that carrying a balance on your credit cards helps with building credit, however, this could not be further from the truth. Credit is built by showing on-time payments, and a low utilization rate, among other factors. What we recommend is for you to try and pay off as much of your balances as possible to help improve your overall credit score.
Credit Card Fees
In this section, we will discuss some credit card fees that you should keep an eye out for every month. It is very important to understand these prior to applying for a new credit card.
Interest Fees
An interest cost, commonly known as a finance charge, will be assessed if you only make the minimum payment rather than clearing the entire statement balance. Depending on your daily average balance, credit card companies calculate interest fees. Once you begin carrying a balance on your card, interest will start to accrue daily and will be applied to this daily average balance over the length of a billing cycle. Avoiding interest is crucial if you're trying to develop credit, especially if you're just getting started.
To determine how much interest you pay daily on your credit card, divide the APR by 365. It's vital to remember that rates vary depending on the customer and the credit card they use. Lower interest rates are available to those with better credit ratings. To make sure you comprehend how your interest is calculated, check the terms of your card.
You may set up online payments that are deducted from your checking or savings account automatically with the majority of credit cards. This is an excellent strategy to prevent late payments because it will assist ensure that your payments are made each month on time or before the due date.
Late Fees
Late fees are assessed only when payments are received after the due date or established grace period if there is one. With a balance, most credit card issuers give you a minimum of 21 days to make the payment before a late fee is assessed. In addition to this, some card issuers use tiered late payments depending on how late your payment is. If you feel that you were assessed a late payment by mistake, The Credit Lion is well versed in helping consumers remove inaccurate records from their credit reports. Please feel free to schedule a courtesy consultation with a credit specialist!
The bottom line
At the end of the day, the most important part of your credit profile is your payment history. Please make sure that you are paying your cards on time, and that you are paying off as much of your balances as possible. Doing so will help you raise your credit score, and hopefully gain approval for future lines of credit!